Pages

Subscribe:

Ads 468x60px

Showing posts with label interest. Show all posts

Thursday, June 7, 2012

$Pound Outperforms as BoE Holds Interest Rate, Easing Unchanged

 THE TAKEAWAY: Bank of England says interest rates, quantitative easing unchanged -> China cuts interest rates for the first time since 2008 -> UK Pound climbs against US Dollar
The Bank England decided today to keep its monetary policy steady at the end of its 2 day deliberation process, sparking a wave of outperformance in Sterling and invalidating speculation that the central bank would take a more dovish stance.
The June benchmark interest rate will remain unchanged at 0.50%, and the BoE’s quantitative easing target will stay at 325 billion pounds. Although economists did not expect a change today, speculation that the central bank would adopt further accommodative measures had grown recently on news of the worsening political crisis in Europe.
Even so, further easing in the months to come cannot be ruled out. The Bank of England’s most recent monthly inflation report said “the possibility that the substantial challenges within the Euro area will lead to significant economic and financial disruption continues to pose the greatest threat to the UK recovery.”
Pound_Outperforms_as_BoE_Holds_Interest_Rate_Easing_Unchanged_body_BOE.png, Pound Outperforms as BoE Holds Interest Rate, Easing Unchanged

The British pound spiked on the news that further easing will be delayed for at least a month. The Pound was strong against the Euro and US Dollar directly after the report.

Wednesday, May 9, 2012

£/$ GBPUSD: Trading of the Bank of England interest rate decision

Trading the News: Bank of England Interest Rate Decision
What’s Expected:
Time of release: 05/10/2012 11:00 GMT, 7:00 EDT
Primary Pair Impact: GBPUSD
Expected: 325B
Previous: 325B
DailyFX Forecast: 325B
Why Is This Event Important:
Although the Bank of England is widely expected to maintain its current policy stance in May, the bullish sentiment underlining the British Pound may gather pace as the central bank adopts a hawkish tone for monetary policy. As the BoE preserve its wait-and-see approach, we may see the Monetary Policy Committee refrain from releasing a policy statement, but the quarterly inflation on tap for May 16 may trigger fresh highs in the GBPUSD should the central bank raise its fundamental assessment for the U.K. Indeed, we should see the MPC move away from its easing cycle as BoE officials anticipate to see a faster recovery in the second-half of the year, and the board may start to lay out a tentative exit strategy as the stickiness in underlying price growth raises the risk for inflation.
Recent Economic Developments
Release
Expected
Actual
Retail Sales ex Auto Fuel (MoM) (MAR)
0.4%
1.5%
Consumer Price Index (YoY) (MAR)
3.4%
3.5%
Producer Price Index - Outputs (YoY) (MAR)
3.5%
3.6%
The Downside
Release
Expected
Actual
Halifx House Prices (3MoY) (APR)
0.4%
-0.5%
Gross Domestic Product (QoQ) (1Q A)
0.1%
-0.2%
Average Weekly Earnings (3MoY) (FEB)
1.2%
1.1%


As the outlook for growth and inflation picks up, we should see the BoE adopt a hawkish tone for monetary policy, and a fresh batch of central bank rhetoric may spark fresh highs in the GBPUSD as market participants start to look for a rate hike. However, the ongoing slack within the real economy paired with the slowdown in wage growth may encourage the BoE to strike a balanced tone for the region, and we may see the central bank carry its current policy stance into the second-half of the year as the recession in the euro-area – Britain’s largest trading partner – dampens the outlook for growth. In turn, a neutral policy statement may halt the bullish run in the GBPUSD, and the pair may ultimately face range-bounce prices as market participants maintain bets for more easing.

Potential Price Targets For The Rate Decision

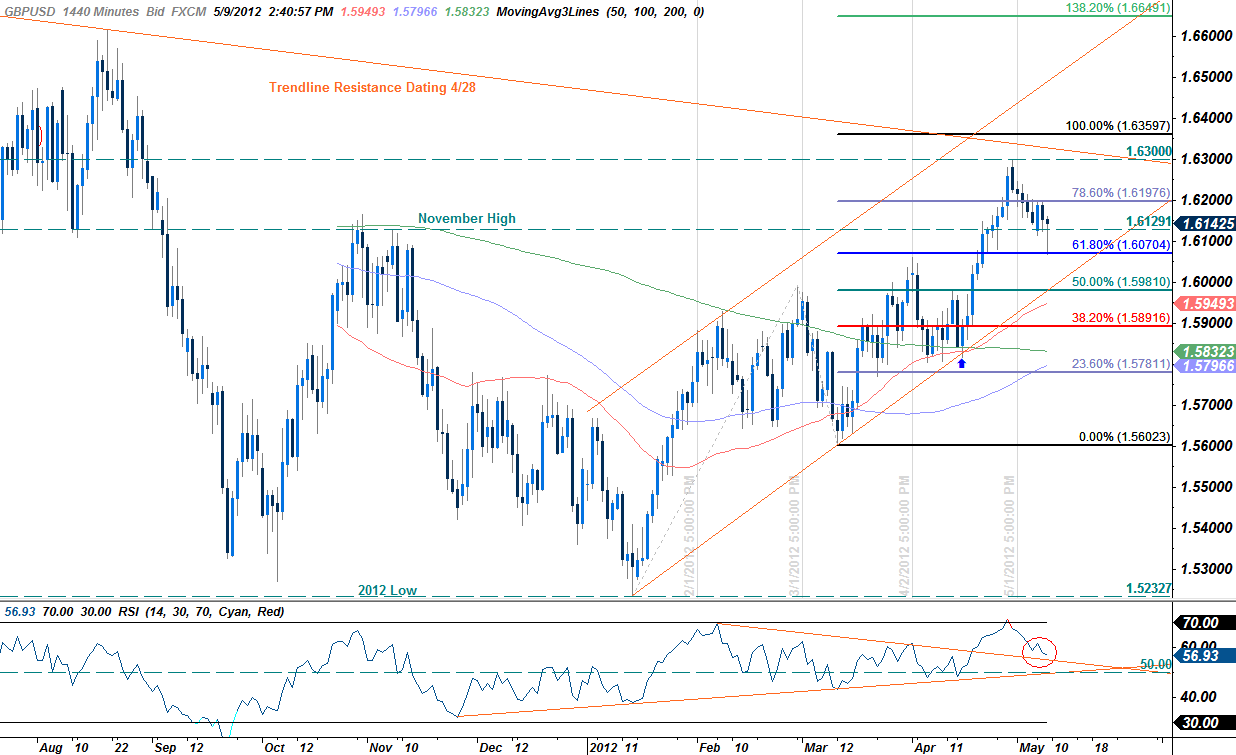
GBPUSD_Trading_the_Bank_of_England_Interest_Rate_Decision_body_05.png, GBPUSD: Trading the Bank of England Interest Rate DecisionA look at the encompassing structure sees the pound continuing to trade within the confines of a well-defined ascending channel formation dating back to the January low with the downside correction off the 2012 high at 1.63 finding ample support at the 61.8% Fibonacci extension taken from the January and March troughs at 1.6070. While our medium-term bias remains weighted to the topside, it’s important to note that broader risk trends may continue to drag on the pound, limiting advances in the near-term. We continue to favor long entries between the 1.60-handle (channel support) and the 1.6070-mark with a breach above the 78.6% extension at the 1.62-figure dispelling further downside pressure. Such a scenario eyes topside targets at the 1.63-handle and the 100% extension at 1.6360.

GBPUSD_Trading_the_Bank_of_England_Interest_Rate_Decision_body_05_1.png, GBPUSD: Trading the Bank of England Interest Rate Decision
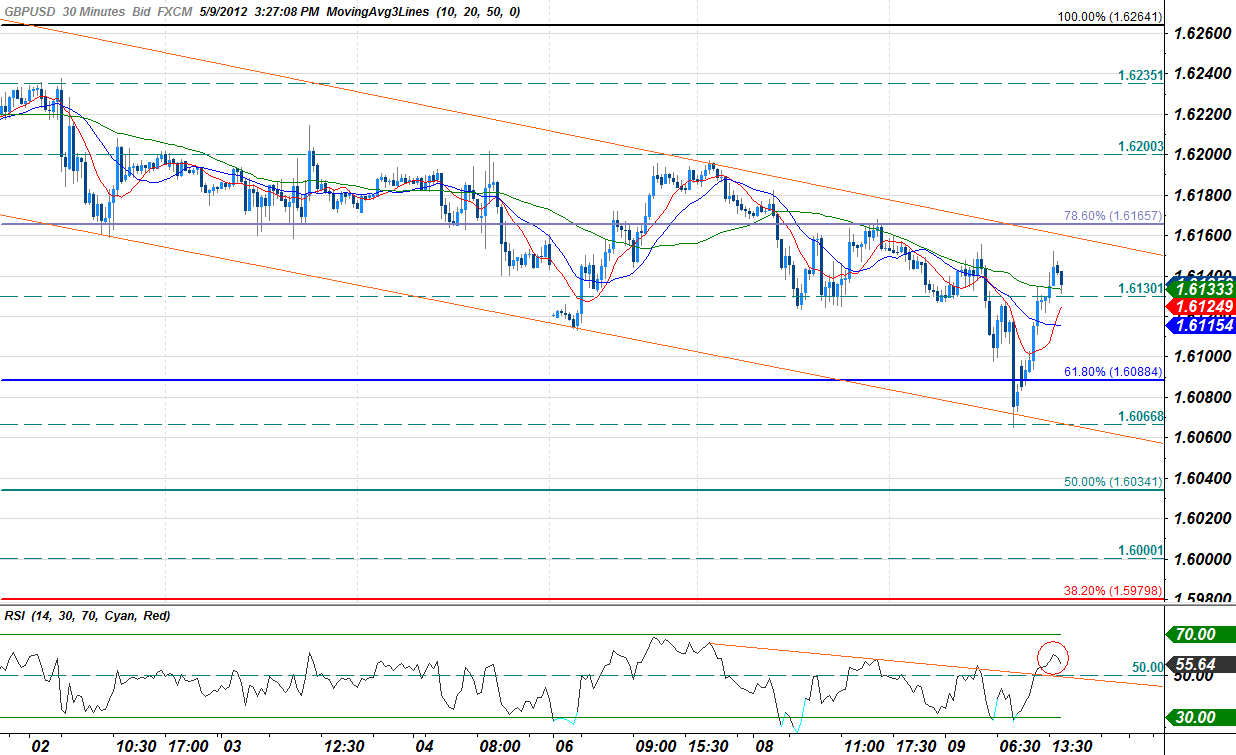
The scalp chart shows the GBPUSD holding within the confines of a descending channel formation dating back to the April 30th high with the pair testing channel support early in the US session. Soft interim support rests at 1.6130 backed by the 61.8% Fibonacci extension taken from the March 12th and April 5th troughs at 1.6088 and 1.6065. A break below the 50% extension at 1.6035 risks further losses for the pound with subsequent floors seen at the 1.60-figure and the 38.2% extension at 1.5980. A breach above channel resistance targets the 78.6% extension at 1.6165, the 1.62-figure, 1.6235 and the 100% extension at 1.6265, with a breach above the 2012 high at 1.63 exposing our objective at 1.6360. As the BoE maintains its current policy we may see a muted reaction to the release. However we will be closely eyeing these levels as we head into the quarterly inflation report due out on May 16th.
How To Trade This Event Risk
Trading the BoE rate decision may not be as clear cut as some of our previous trades as the BoE is widely expected to preserve its current policy stance, but a hawkish policy statement could set the stage for a long British Pound trade as it raises the scope for a rate hike. Therefore, if the central bank sees a greater risk for inflation and continues to favor a stronger recovery for the second-half of 2012, we will need a green, five-minute candle following the decision to generate a buy entry on two-lots of GBPUSD. Once these conditions are fulfilled, we will set the initial stop at the nearby swing low or a reasonable distance from the entry and this risk will establish our first target. The second objective will be based on discretion, and we will move the stop on the second lot to cost once the first trade hits its mark in order to preserve our profits.
On the other hand, we may see board member David Miles continue to push for more quantitative easing amid the ongoing slack within the real economy, and the majority may carry its neutral policy stance into the third-quarter in an effort to encourage a stronger recovery. As a result, if we see a growing rift within the MPC, with the board highlighting the downside risks surrounding the region, we will carry out the same strategy for a short pound-dollar trade as the short position laid out above, just in reverse.
Impact that the Bank of England Interest Rate Decision has had on GBP during the last meeting
Pips Change
(1 Hour post event )
Pips Change
(End of Day post event)
April 2102 Bank of England Interest Rate Decision
Period
Data Released
Estimate
Actual
Pips Change
(1 Hour post event )
Pips Change
(End of Day post event)
APR 2012
04/05/2012 11:00 GMT
325B
325B
+26
+4

GBPUSD_Trading_the_Bank_of_England_Interest_Rate_Decision_body_ScreenShot029.png, GBPUSD: Trading the Bank of England Interest Rate Decision
As expected, the Bank of England preserved its current policy in April, which produced a fairly muted reaction in the British Pound, but the meeting minutes sparked a sharp rally in the GBPUSD as the MPC voted 8-1 to keep the benchmark interest rate at 1.00% while holding the asset purchase target at GBP 325B. Indeed, board member Adam Posen scaled back his view for more QE as BoE officials expect to see a stronger recovery later this year, and it seems as though the central bank is looking to conclude its easing cycle this year as the committee no longer sees a risk of undershooting the 2% target for inflation.

Thursday, May 3, 2012

€/$ EURUSD: Trading the European Central Bank Interest Rate Decision

Trading the News: European Central Bank Interest Rate Decision
What’s Expected:
Time of release: 05/03/2012 11:45 GMT, 7:45 EDT
Primary Pair Impact: EURUSD
Expected: 1.00%
Previous: 1.00%
DailyFX Forecast: 1.00%
Why Is This Event Important:
Although the European Central Bank is widely expected to keep the benchmark interest rate at 1.00%, the fresh batch of comments from President Mario Draghi could drag on the EURUSD should the central bank head show an increased willingness to expand monetary policy further. As the sovereign debt crisis continues to dampen the outlook for the euro-area, the policy statement may sound a bit more dovish this time around, and the Governing Council may look to target the benchmark interest rate as the slew of non-standard measures appear to be having a limited impact on the real economy. As the threat for a prolonged recession casts a bearish outlook for the single currency, the rate decision could serve as a catalyst to spark a sharp selloff in the EURUSD, and the bearish formation should continue to take shape as price action approaches the apex of the descending triangle.
Recent Economic Developments
The Upside
Euro-Zone Consumer Price Index Estimate (YoY) (APR)
Euro-Zone Consumer Price Index (YoY) (MAR)
Euro-Zone Producer Price Index (YoY) (FEB)
The Downside
Euro-Zone Unemployment Rate (MAR)
Euro-Zone Purchasing Manager Index Composite (APR A)
Euro-Zone Gross Domestic Product (QoQ) (4Q P)
Despite the weakening outlook for the euro-area, heightening price pressures may encourage the ECB to draw up a more balanced tone for the region, and the central bank may endorse a wait-and-see approach throughout the first-half of the year as it preserve its one and only mandate to ensure price stability. However, the ongoing weakness in the labor market paired with fears of a deep recession may bring about a very dovish policy statement, and the Governing Council may look to carry its easing cycle into the second-half of the year in an effort to encourage a stronger recovery.
Potential Price Targets For The Rate Decision

EURUSD_Trading_the_European_Central_Bank_Interest_Rate_Decision_body_05.png, EURUSD: Trading the European Central Bank Interest Rate Decision A look at the encompassing structure sees the EURUSD trading within the confines of a broad descending channel formation dating back to the August highs with the single currency rebounding off channel resistance of an embedded channel dating back to the February highs. Key daily resistance stands at the 1.33 figure with a breach above this level challenging the 1.34-figure and the February highs at 1.3485. Daily support rests with the 100-day moving average at 1.3115 and the 1.30-figure.

EURUSD_Trading_the_European_Central_Bank_Interest_Rate_Decision_body_05_1.png, EURUSD: Trading the European Central Bank Interest Rate Decision The scalp charts shows somewhat of a mixed outlook for the EURUSD. Clear bearish divergence in the relative strength index alluded to the euro’s decline today with the single currency rebounding off the 38.2% Fibonacci extension taken from the March 27th and May 1st crests at 1.3130 before encountering soft resistance at 1.3165. Subsequent resistance levels are eyed at the 23.6% extension at 1.3190 backed by 1.3210, 1.3240 and 1.3260. A breach above the May 1st high at 1.3280 negates this specific setup with such a scenario eyeing targets above the 1.33-handle. Interim support rests with the 38.2% extension with support targets seen lower at 1.3110, the 50% extension at 1.3085 and 1.3060. The initial objective remains the 1.30 figure which has been met with sharp rebounds over the past three months each time the level has been tested. Should the print prompt a bearish response look to target downside levels with a break below the 1.30-threshold offering further conviction on our directional bias.
How To Trade This Event Risk
Trading the interest rate decision may not be as clear cut as some of our previous trades as ECB President Mario Draghi is scheduled to speak at 12:30 GMT, but the policy statement may pave the way for a long Euro trade should the central bank strike a balanced outlook for the region. Therefore, if Mr. Draghi talks down the risks surrounding the region and highlights the recent pick up in price growth, we will need a green, five-minute candle following the release to generate a buy entry on two-lots of EURUSD. Once these conditions are met, we will set the initial stop at the nearby swing low or a reasonable distance from the entry, and this risk will establish our first target. The second objective will be based on discretion, and we will move the stop on the second lot to breakeven once the first trader hits its mark in order to protect our profits.
In contrast, the ongoing weakness in the real economy paired with the threat for contagion may ultimately lead to a very dovish ECB, and we may see the central bank head may endorse the easing cycle as the fundamental outlook for the region remains bleak. As a result, if the Governing Council opens the door for additional monetary support, we will implement the same setup for a short euro-dollar trade as the long position laid out above, just in the opposite direction.
Impact that the European Central Bank Interest Rate Decision has had on EUR during the last meeting
Pips Change
(1 Hour post event )
Pips Change
(End of Day post event)
April 2012 European Central Bank Interest Rate Decision

EURUSD_Trading_the_European_Central_Bank_Interest_Rate_Decision_body_ScreenShot114.png, EURUSD: Trading the European Central Bank Interest Rate Decision As expected, the European Central Bank struck a cautious outlook for the region after keeping the benchmark interest rate at 1.00%, while central bank President Mario Draghi argued that ‘any exit strategy talk for the time being is premature’ as the region faces a double-dip recession. The dovish tone held by the ECB dragged on the Euro, with the EURUSD falling back towards the 1.3100 figure, but we saw the single currency consolidate during the North America trade to end the day at 1.3140.

Tuesday, February 7, 2012

Commerce Bank of reserve of the Australia interest rate decision

The request channel timed out while waiting for a reply after 00: 01: 00. Increase the timeout value passed to the call to Request or increase the SendTimeout value on the Binding. The time allotted to this operation may have been a portion of a longer timeout.
February 6th, 1: 41 pm by Sam
The Reserve Bank of Australia is scheduled to announce its interest rate decision at 3: 30 am London time on February 7th. Analysts are forecasting that the RBA will cut rates by 25 basis points. Australia has been one of the best performing economies in 2011 despite a global financial crisis due to the sovereign debt issues in Europe. The Australian Dollar has gained nearly 800 pips against the U.S. Dollar since the last rate decision. The RBA has delivered two consecutive rate cuts of 25 basis points in November and December; However the Aussie continues to attract safe haven capital flow because of the strong local economy.
OpenBook top trader waleed0987 has been bearish on the AUDUSD. While this trader has been trading against the trend, he has managed to squeeze small profits from his short positions between 2% and 8%. Ahead of the RBA rate decision, this trader has a short AUDUSD position with target at 1.0462. Trader waleed0987 has 1438 copiers and 8872 followers on OpenBook.

Recent Australian Economic developments to take in consideration
Australia reported a trade surplus of $1.7 million in December, an increase of $366 million in surplus from November. The unemployment rate held at 5.2% in December. CPI rose 3.1% on an annual basis in the fourth quarter compared to a rise of 3.5% on an annual basis in the third quarter.
Market Reaction to previous RBA rate decision
At its last policy meeting, the AUDUSD dropped 60 pips immediately after the rate cut was announced.
Scenario A: RBA cuts rates by 25 basis points
This scenario is widely expected. In this scenario, the AUDUSD might drop 60 pips after the rate decision
Scenario B: RBA cuts rates by 50 basis points
If the RBA believes that the situation in Europe does not have a quick fix and decides to lower by 50 basis points, we might see the AUDUSD drop by 100 pips.
Scenario C: RBA leaves rates unchanged
If the RBA takes a neutral stance, we might see the AUDUSD continued its trend and rally higher towards 1.1000.
OpenBook:
Traders on OpenBook are primarily bearish on AUDUSD with average limits at 1. 0550and stops at 1.0800.
OpenBook trader molla01 is a single trader as this trader focuses on trading just the AUDUSD. The trader has had an impressive run so far with 170% returns in the last seven days and 749% returns in the last thirty days. This trader has been trading on a 100 pip move in the hand by shorting near 1.0540 and closing near 1.0444. This strategy has netted the trader close to 95% returns with his medium risk strategy. The trader has also been looking for buying opportunities near 1.0690 and closing near 1.0760 with gains near 100%. This trader has also built up a sizeable long exposure on the AUDUSD and is expecting the hand to target 1.0670. While the vast majority of traders are bearish on AUDUSD, this trader has simply followed the AUDUSD trend and looked for buying opportunities. With 76.3% of this trader's trades in the buy direction, we are waiting to see if this trader will switch his opinion depending on the RBA rate decision. This trader has 4 copiers and 28 followers on OpenBook.

Wednesday, February 1, 2012

TradeTheNews.com European Market Update: Risk appetite buoyed by reports that private lenders said to have accepted lower interest rate in Greek PSI deal


 TradeTheNews.com European Market Update: Risk appetite buoyed by reports that private lenders said to have accepted lower interest rate in Greek PSI deal

***Economic Data***
- (EU) ECB: €3.5B borrowed in overnight loan facility v €3.6B prior; €484.1B parked in deposit facility vs. €485.8B prior
- (RU) Russia Gold & Forex Reserve w/e Jan 20th: $499.7B v $497.1B prior
- (DE) Germany Feb GfK Consumer Confidence Survey: 5.9 v 5.6e
- (FR) France Jan Consumer Confidence: 81 v 80e
- (DK) Denmark Dec Unemployment Rate: 4.0% v 4.3%e; Gross Unemployment Rate: 6.1% v 6.3%e
- (SE) Sweden Jan Consumer Confidence: -1.3 v -7.0e; Manufacturing Confidence: -14 v -11e; Economic Tendency Survey: 91.4 v 93.0e
- (HK) Hong Kong Dec Trade Balance (HKD): -48.9B v -54.4e; Exports Y/Y: 7.4% v 3.5%e; Imports Y/Y: 8.1% v 6.6%e
- (SE) Sweden Dec PPI M/M: -0.2% v -0.4%e; Y/Y: -2.1% v -2.3%e
- (SE) Sweden Dec Trade Balance (SEK): 2.8B v 6.5Be
- (SE) Sweden Dec Unemployment Rate: 7.1% v 7.0%e
- (IT) Italy Jan Consumer Confidence: 91.6 v 92.0e
- (ZA) South Africa Dec PPI M/M: 0.0% v 0.2%e; Y/Y: 9.8% v 10.0e%e
- (IT) Italy Dec Hourly Wages M/M: 0.0% v 0.0% prior; Y/Y: 1.4% v 1.5% prior
- (BR) Brazil Jan FGV Construction Costs M/M: 0.7% v 0.7%e
- (BR) Brazil Dec Unemployment Rate: 4.7% v 4.9%e
- (UK) Jan CBI Industrial Reported Sales: -22 v -6e
- (IE) Ireland Dec PPI M/M: 0.5 v 0.9% prior; Y/Y: 2.4% v 1.9% prior


Fixed Income:
- (IT) Italy Debt Agency (Tesoro) sold €4.5B vs. €4.5B indicated in new Zero Coupon 2014 CTZ; Avg Yield 3.673% v 4.853% prior; Bid-to-cover: 1.7x v 2.24x prior
- (IT) Italy Debt Agency (Tesoro) sold €500M v €250-500M indicated range in 2.15% 2014 I/L Bonds; Yield 3.20%; Bid-to-cover: 2.79x
- (HU) Hungary Debt Agency (AKK) sold total HUF48B in 2014, 2017 and 2022 Bonds


*** SPEAKERS/FIXED INCOME/FX/COMMODITIES/ERRATUM ***
***Notes/Observations***
- Fed Chairman Bernanke signals years of low interest rates ahead with potential more stimulus. Fed stance appears to be pro inflationary
- Dow approaching 3 highs
- US Tsy Sec Geithner will not participate in any Obama second term
- Reports that private creditors were willing to accept a lower coupon in the PSI negotiations


Equities:
FTSE 100 +1.14% at 5788, DAX +1.36% at 6508, CAC-40 +1.11% at 33491, IBEX-35 +1.36% at 8671, FTSE MIB +1.61% at 16,095, SMI +0.3% at 6090


- European equity indices opened the session higher, as the US Fed disclosed that 11 out of 17 of its members saw the FOMC raising the Fed funds rate in 2014 or later. Ahead of the Fed meeting, there were expectations in the market that the Fed would not raise rates until at least mid-2014. Since the open, indices have continued to gain on renewed optimism related to the Greece private sector involvement talks, after a Greek press report, without citing sources, said Greece's private lenders were said to be willing to accept a coupon rate of below 4% on new Greek bonds. In the past, it was reported that Greece's private lenders were seeking a coupon of at least 4%.
- In individual stocks, French name Plastic Omnium [POM.FR] has gained over 5%, after reporting Q4 sales. In the UK, Anglo American [AAL.UK] and Kazakhmys [KAZ.UK] are higher following the release of their production reports. Misys [MSY.UK] has declined by over 6%, after issuing first half results. German polysilicon name Wacker Chemie [WCH.DE] has moved between gains and losses following the release of its Q4 earnings. In Switzerland, Logitech [LOGN.CH] is down over 10%, as the company's quarterly results missed expectations. Companies due to report later today include, Nokia [NOK1V.FI], Areva [AREVA.FR], Britsol-Myers Squibb [BMY], Caterpillar [CAT], Colgate [CL], 3M [MMM], Potash [POT] and AT&T [T].


Speakers:
- Greek Press report stated that private lenders were said to have accepted lower interest rate in Greek PSI deal with creditors are said to be willing to accept a coupon rate of below 4% on new Greek bonds. The report did not name sources, but said private sector creditors would submit a new improved offer with an avg interest rate of 3.75%. EU finance ministers had been seeking a rate of no more than 3.5% and in the past private lenders said that they would not accept less than 4%.
- German Fin Min Schaeuble reiterated its view that European crisis must be addressed at its source during an address to the Bundestag (lower house). He noted that it was likely that German banks would hit capital goals in June and could fill capital gaps without aid. The SoFFin was preventive medicine for euro zone contagion.
- German Econ Min Roesler commented that the ESM rescue fund had 'clear borderlines' and that there was no clear link with its funding and fiscal pact. Germany was doing every thing possible to defend the Euro
- Senior German Official commented that Greece was not on the agenda at the Jan 30th EU Leader Summit and did not expect Troika report on second package for Greece to be ready by then
- (ES) Spain Budget Min Montoro commented that Spain was in a recession and it was worse than Europe's
- Russian Central Bank Deputy Ulyukaev commented that inflationary risks have not disappeared and that conditions were not appropriate for an interest rate cut. On the reserve currency issue, Russia might diversify into AUD assets in early Feb
- Turkey Central Bank Gov Basci commented that he believed 2012 GDP growth of 4% could be easily achieved and no serious risk of inflation. The IMF forecast of Turkey stressed downside risks. He noted that Turkey had compensated for TRY currency depreciation
- Turkey Econ Min Babacan commented that there was no need to revise Turkey's economic forecasts and that 2011 GDP growth exceeded 8%. He stated that the country's central bank was not causing inflation as higher interest rates reflected reality and suitable at this time but not in the long run. Turkey was prepared for any outcome with a flexible policy but could not allow fiscal loosening. - Not yet concerned about the country's currency reserves and Turkey was still drawing foreign exchange inflows. He had no major concerns on the TRY currency rate (Lira) with no target in mind
- IMF's Brekk commented that Russia should target medium term inflation between 3-5% and forecasted Russia economic medium-term growth between 3.5-40% without enacting reforms. Russia's pension spending is on an unsustainable path
- Cyprus Fin Min Kazamias commented that it received a second Russian loan payment to be used for bond redemptions with a third installment expected by the end of March
- OECD trimmed its Denmark 2012 and 2013 GDP growth outlook and noted that international economic slowdown posed new risks for Denmark. The country's economy was growing slowly and uneven from the financial crisis while its fiscal position was relatively sound
- WTO's Lamy: CNY currency remains undervalued but no consensus by exactly how much
- Iranian policy maker Emad Hosseini said lawmakers' were finalizing a bill to stop all oil trade with Europe
- Brazil Central Bank (COPOM) Monetary Policy Meeting Minutes noted that recent data suggested that inflation was on a declining trend with a "high" chance of SELIC rate moving below 10%


Currencies:
- FX markets continued to digest the impact of the Fed's extended zero policy guidance from Wednesday. The overall effect has seen a weaker USD coupled with renewed risk appetite and higher commodity prices. The greenback was at one-month lows against the Euro and GBP and two-month lows against the CHF.
- The EUR/USD maintained a foothold above the 1.31 handle and dealers noted that it had the technical legs to probe above 1.32. There were some initial concerns that Greek debt negotiations and renewed Portugal bailout would provide some headwinds for the pair. However, press reports that the private lenders were said to have accepted lower interest rate in Greek PSI deal provided additional momentum for risk appetite and the Euro. The EUR/USD tested above the 1.3170 level during the session as a result. USD/CHF tested below 0.9170 while GBP/USD probed above 1.57 handle. Precious metals were firmer with spot gold at $1,715/oz and spot Silver testing above $33.50/oz


Political/ In the Papers:
- The Irish Independent confirmed that the EU Commission will 'carefully consider' Ireland's bid to cut the Anglo Irish Bank's bailout costs. The ECB said it is open to proposals to replace Anglo Irish Bank's €30B promissory note, or government IOUs for another instrument. Ireland is paying around 6% (although it could be refinanced at 3% by the EFSF) on the outstanding €31B in promissory notes, issued mostly to deal with the collapse of Anglo Irish Bank.
- Iranian policy maker Emad Hosseini said lawmakers are finalizing a bill to stop all oil trade with Europe. The FT reported that according to Hosseini, if the plan is approved, the government will stop oil sales to Europe before the EU begins its embargo. The bill could be taken up by parliament before Sunday. On January 23rd, EU officials agreed to impose an embargo on Iranian oil, including plans to ban Iran's petrochemical shipments from May 1st.

***Looking Ahead***
- (CH) World Economic Forum held in Davos, Switzerland
- (PT) Bank of Portugal publishes Bank Survey on Credit Market
- (US) Republican primary debate in Jacksonville, Florida
- 6:15 (EU) EU's Barroso
- 6:30 (DE) German Chancellor Merkel hosts Spanish PM Rajoy in Berlin
- 8:30 (US) Dec Chicago Fed National Activity Index: -0.10e v -0.37 prior
- 8:30 (US) Dec Durable Goods Orders: 2.0%e v 3.7% prior (revised from 3.8%); Durables Ex Transportation: 0.9%e v 0.3% prior
- 8:30 (US) Initial Jobless Claims: 370Ke v 352K prior; Continuing Claims: 3.50Me v 3.432M prior
- 9:00 (MX) Mexico Nov Retail Sales: No est v 3.0% prior
- 10:00 (US) Revisions of Leading Indicators
- 10:00 (US) Dec Leading Indicators: 0.7%e v 0.5% prior
- 10:00 (US) Dec New Home Sales 321Ke v 315K prior
- 10:30 (US) Weekly EIA Natural Gas Inventories
- 11:00 (US) Jan Kansas City Fed Manufacturing Activity: +2e v -4 prior
- 11:00 (US) Fed to purchase $2.25-2.75B in Notes
- 12:00 (CA) Canada Treasury Board President Clement speaks in Toronto
- 13:00 (US) Treasury to sell $29.0B in 7-Year Notes
- 14:30 (FR) Socialist Presidential Runner Hollande details platform on TV
- 16:00 (KR) South Korea Feb Manufacturing Business Survey: No est v 79 prior; Non-Manufacturing: No est v 79 prior
- 16:00 (KR) South Korea Jan Consumer Confidence: No est v 99 prior

Legal disclaimer and risk disclosure

All information provided by Trade The News (a product of Trade The News, Inc. "referred to as TTN hereafter") is for informational purposes only. Information provided is not meant as investment advice nor is it a recommendation to Buy or Sell securities. Although information is taken from sources deemed reliable, no guarantees or assurances can be made to the accuracy of any information provided. 1. Information can be inaccurate and/or incomplete 2. Information can be mistakenly re-released or be delayed, 3. Information may be incorrect, misread, misinterpreted or misunderstood 4. Human error is a business risk you are willing to assume 5. Technology can crash or be interrupted without notice 6. Trading decisions are the responsibility of traders, not those providing additional information. Trade The News is not liable (financial and/or non-financial) for any losses that may arise from any information provided by TTN. Trading securities involves a high degree of risk, and financial losses can and do occur on a regular basis and are part of the risk of trading and investing.

Daily Forex Market News
Forex news reports can be found on the forex research headlines page below. Here you will find real-time forex market news reports provided by respected contributors of currency trading information. Daily forex market news, weekly forex research and monthly forex news features can be found here.

Forex News
Real-time forex market news reports and features providing other currency trading information can be accessed by clicking on any of the headlines below. At the top of the forex blog page you will find the latest forex trading information. Scroll down the page if you are looking for less recent currency trading information. Scroll to the bottom of fx blog headlines and click on the link for past reports on forex. Currency world news reports from previous years can be found on the left sidebar under "FX Archives."


Saturday, January 28, 2012

TradeTheNews.com European Market Update: Risk appetite buoyed by reports that private lenders said to have accepted lower interest rate in Greek PSI deal


 TradeTheNews.com European Market Update: Risk appetite buoyed by reports that private lenders said to have accepted lower interest rate in Greek PSI deal
***Economic Data***
- (EU) ECB: €3.5B borrowed in overnight loan facility v €3.6B prior; €484.1B parked in deposit facility vs. €485.8B prior
- (RU) Russia Gold & Forex Reserve w/e Jan 20th: $499.7B v $497.1B prior
- (DE) Germany Feb GfK Consumer Confidence Survey: 5.9 v 5.6e
- (FR) France Jan Consumer Confidence: 81 v 80e
- (DK) Denmark Dec Unemployment Rate: 4.0% v 4.3%e; Gross Unemployment Rate: 6.1% v 6.3%e
- (SE) Sweden Jan Consumer Confidence: -1.3 v -7.0e; Manufacturing Confidence: -14 v -11e; Economic Tendency Survey: 91.4 v 93.0e
- (HK) Hong Kong Dec Trade Balance (HKD): -48.9B v -54.4e; Exports Y/Y: 7.4% v 3.5%e; Imports Y/Y: 8.1% v 6.6%e
- (SE) Sweden Dec PPI M/M: -0.2% v -0.4%e; Y/Y: -2.1% v -2.3%e
- (SE) Sweden Dec Trade Balance (SEK): 2.8B v 6.5Be
- (SE) Sweden Dec Unemployment Rate: 7.1% v 7.0%e
- (IT) Italy Jan Consumer Confidence: 91.6 v 92.0e
- (ZA) South Africa Dec PPI M/M: 0.0% v 0.2%e; Y/Y: 9.8% v 10.0e%e
- (IT) Italy Dec Hourly Wages M/M: 0.0% v 0.0% prior; Y/Y: 1.4% v 1.5% prior
- (BR) Brazil Jan FGV Construction Costs M/M: 0.7% v 0.7%e
- (BR) Brazil Dec Unemployment Rate: 4.7% v 4.9%e
- (UK) Jan CBI Industrial Reported Sales: -22 v -6e
- (IE) Ireland Dec PPI M/M: 0.5 v 0.9% prior; Y/Y: 2.4% v 1.9% prior

Fixed Income:
- (IT) Italy Debt Agency (Tesoro) sold €4.5B vs. €4.5B indicated in new Zero Coupon 2014 CTZ; Avg Yield 3.673% v 4.853% prior; Bid-to-cover: 1.7x v 2.24x prior
- (IT) Italy Debt Agency (Tesoro) sold €500M v €250-500M indicated range in 2.15% 2014 I/L Bonds; Yield 3.20%; Bid-to-cover: 2.79x
- (HU) Hungary Debt Agency (AKK) sold total HUF48B in 2014, 2017 and 2022 Bonds
*** SPEAKERS/FIXED INCOME/FX/COMMODITIES/ERRATUM ***
***Notes/Observations***
- Fed Chairman Bernanke signals years of low interest rates ahead with potential more stimulus. Fed stance appears to be pro inflationary
- Dow approaching 3 highs
- US Tsy Sec Geithner will not participate in any Obama second term
- Reports that private creditors were willing to accept a lower coupon in the PSI negotiations
Equities:
FTSE 100 +1.14% at 5788, DAX +1.36% at 6508, CAC-40 +1.11% at 33491, IBEX-35 +1.36% at 8671, FTSE MIB +1.61% at 16,095, SMI +0.3% at 6090
- European equity indices opened the session higher, as the US Fed disclosed that 11 out of 17 of its members saw the FOMC raising the Fed funds rate in 2014 or later. Ahead of the Fed meeting, there were expectations in the market that the Fed would not raise rates until at least mid-2014. Since the open, indices have continued to gain on renewed optimism related to the Greece private sector involvement talks, after a Greek press report, without citing sources, said Greece's private lenders were said to be willing to accept a coupon rate of below 4% on new Greek bonds. In the past, it was reported that Greece's private lenders were seeking a coupon of at least 4%.
- In individual stocks, French name Plastic Omnium [POM.FR] has gained over 5%, after reporting Q4 sales. In the UK, Anglo American [AAL.UK] and Kazakhmys [KAZ.UK] are higher following the release of their production reports. Misys [MSY.UK] has declined by over 6%, after issuing first half results. German polysilicon name Wacker Chemie [WCH.DE] has moved between gains and losses following the release of its Q4 earnings. In Switzerland, Logitech [LOGN.CH] is down over 10%, as the company's quarterly results missed expectations. Companies due to report later today include, Nokia [NOK1V.FI], Areva [AREVA.FR], Britsol-Myers Squibb [BMY], Caterpillar [CAT], Colgate [CL], 3M [MMM], Potash [POT] and AT&T [T].
Speakers:
- Greek Press report stated that private lenders were said to have accepted lower interest rate in Greek PSI deal with creditors are said to be willing to accept a coupon rate of below 4% on new Greek bonds. The report did not name sources, but said private sector creditors would submit a new improved offer with an avg interest rate of 3.75%. EU finance ministers had been seeking a rate of no more than 3.5% and in the past private lenders said that they would not accept less than 4%.
- German Fin Min Schaeuble reiterated its view that European crisis must be addressed at its source during an address to the Bundestag (lower house). He noted that it was likely that German banks would hit capital goals in June and could fill capital gaps without aid. The SoFFin was preventive medicine for euro zone contagion.
- German Econ Min Roesler commented that the ESM rescue fund had 'clear borderlines' and that there was no clear link with its funding and fiscal pact. Germany was doing every thing possible to defend the Euro
- Senior German Official commented that Greece was not on the agenda at the Jan 30th EU Leader Summit and did not expect Troika report on second package for Greece to be ready by then
- (ES) Spain Budget Min Montoro commented that Spain was in a recession and it was worse than Europe's
- Russian Central Bank Deputy Ulyukaev commented that inflationary risks have not disappeared and that conditions were not appropriate for an interest rate cut. On the reserve currency issue, Russia might diversify into AUD assets in early Feb
- Turkey Central Bank Gov Basci commented that he believed 2012 GDP growth of 4% could be easily achieved and no serious risk of inflation. The IMF forecast of Turkey stressed downside risks. He noted that Turkey had compensated for TRY currency depreciation
- Turkey Econ Min Babacan commented that there was no need to revise Turkey's economic forecasts and that 2011 GDP growth exceeded 8%. He stated that the country's central bank was not causing inflation as higher interest rates reflected reality and suitable at this time but not in the long run. Turkey was prepared for any outcome with a flexible policy but could not allow fiscal loosening. - Not yet concerned about the country's currency reserves and Turkey was still drawing foreign exchange inflows. He had no major concerns on the TRY currency rate (Lira) with no target in mind
- IMF's Brekk commented that Russia should target medium term inflation between 3-5% and forecasted Russia economic medium-term growth between 3.5-40% without enacting reforms. Russia's pension spending is on an unsustainable path
- Cyprus Fin Min Kazamias commented that it received a second Russian loan payment to be used for bond redemptions with a third installment expected by the end of March
- OECD trimmed its Denmark 2012 and 2013 GDP growth outlook and noted that international economic slowdown posed new risks for Denmark. The country's economy was growing slowly and uneven from the financial crisis while its fiscal position was relatively sound
- WTO's Lamy: CNY currency remains undervalued but no consensus by exactly how much
- Iranian policy maker Emad Hosseini said lawmakers' were finalizing a bill to stop all oil trade with Europe
- Brazil Central Bank (COPOM) Monetary Policy Meeting Minutes noted that recent data suggested that inflation was on a declining trend with a "high" chance of SELIC rate moving below 10%
Currencies:
- FX markets continued to digest the impact of the Fed's extended zero policy guidance from Wednesday. The overall effect has seen a weaker USD coupled with renewed risk appetite and higher commodity prices. The greenback was at one-month lows against the Euro and GBP and two-month lows against the CHF.
- The EUR/USD maintained a foothold above the 1.31 handle and dealers noted that it had the technical legs to probe above 1.32. There were some initial concerns that Greek debt negotiations and renewed Portugal bailout would provide some headwinds for the pair. However, press reports that the private lenders were said to have accepted lower interest rate in Greek PSI deal provided additional momentum for risk appetite and the Euro. The EUR/USD tested above the 1.3170 level during the session as a result. USD/CHF tested below 0.9170 while GBP/USD probed above 1.57 handle. Precious metals were firmer with spot gold at $1,715/oz and spot Silver testing above $33.50/oz
Political/ In the Papers:
- The Irish Independent confirmed that the EU Commission will 'carefully consider' Ireland's bid to cut the Anglo Irish Bank's bailout costs. The ECB said it is open to proposals to replace Anglo Irish Bank's €30B promissory note, or government IOUs for another instrument. Ireland is paying around 6% (although it could be refinanced at 3% by the EFSF) on the outstanding €31B in promissory notes, issued mostly to deal with the collapse of Anglo Irish Bank.
- Iranian policy maker Emad Hosseini said lawmakers are finalizing a bill to stop all oil trade with Europe. The FT reported that according to Hosseini, if the plan is approved, the government will stop oil sales to Europe before the EU begins its embargo. The bill could be taken up by parliament before Sunday. On January 23rd, EU officials agreed to impose an embargo on Iranian oil, including plans to ban Iran's petrochemical shipments from May 1st.
***Looking Ahead***
- (CH) World Economic Forum held in Davos, Switzerland
- (PT) Bank of Portugal publishes Bank Survey on Credit Market
- (US) Republican primary debate in Jacksonville, Florida
- 6:15 (EU) EU's Barroso
- 6:30 (DE) German Chancellor Merkel hosts Spanish PM Rajoy in Berlin
- 8:30 (US) Dec Chicago Fed National Activity Index: -0.10e v -0.37 prior
- 8:30 (US) Dec Durable Goods Orders: 2.0%e v 3.7% prior (revised from 3.8%); Durables Ex Transportation: 0.9%e v 0.3% prior
- 8:30 (US) Initial Jobless Claims: 370Ke v 352K prior; Continuing Claims: 3.50Me v 3.432M prior
- 9:00 (MX) Mexico Nov Retail Sales: No est v 3.0% prior
- 10:00 (US) Revisions of Leading Indicators
- 10:00 (US) Dec Leading Indicators: 0.7%e v 0.5% prior
- 10:00 (US) Dec New Home Sales 321Ke v 315K prior
- 10:30 (US) Weekly EIA Natural Gas Inventories
- 11:00 (US) Jan Kansas City Fed Manufacturing Activity: +2e v -4 prior
- 11:00 (US) Fed to purchase $2.25-2.75B in Notes
- 12:00 (CA) Canada Treasury Board President Clement speaks in Toronto
- 13:00 (US) Treasury to sell $29.0B in 7-Year Notes
- 14:30 (FR) Socialist Presidential Runner Hollande details platform on TV
- 16:00 (KR) South Korea Feb Manufacturing Business Survey: No est v 79 prior; Non-Manufacturing: No est v 79 prior
- 16:00 (KR) South Korea Jan Consumer Confidence: No est v 99 prior
Legal disclaimer and risk disclosure
All information provided by Trade The News (a product of Trade The News, Inc. "referred to as TTN hereafter") is for informational purposes only. Information provided is not meant as investment advice nor is it a recommendation to Buy or Sell securities. Although information is taken from sources deemed reliable, no guarantees or assurances can be made to the accuracy of any information provided. 1. Information can be inaccurate and/or incomplete 2. Information can be mistakenly re-released or be delayed, 3. Information may be incorrect, misread, misinterpreted or misunderstood 4. Human error is a business risk you are willing to assume 5. Technology can crash or be interrupted without notice 6. Trading decisions are the responsibility of traders, not those providing additional information. Trade The News is not liable (financial and/or non-financial) for any losses that may arise from any information provided by TTN. Trading securities involves a high degree of risk, and financial losses can and do occur on a regular basis and are part of the risk of trading and investing.