Pages

Subscribe:

Ads 468x60px

Showing posts with label fresh. Show all posts

Monday, May 28, 2012

-$ USD Eyes Fresh Highs Ahead Of Correction, JPY Preserves Bullish Trend

28 May 2012 15:55 GMT

Index
Last
High
Low
Daily Change (%)
Daily Range (% of ATR)
DJ-FXCM Dollar Index
10180.13
10183.25
10148.44
-0.33
70.80%

USD_Eyes_Fresh_Highs_Ahead_Of_Correction_JPY_Preserves_Bullish_Trend_body_ScreenShot051.png, USD Eyes Fresh Highs Ahead Of Correction, JPY Preserves Bullish Trend
The Dow Jones-FXCM U.S. Dollar Index (Ticker: USDollar) is 0.33 percent lower from the open after moving 71 percent of its average true range, but we may see the dollar carve out a fresh high going into June as the upward trending channel from earlier this month continues to take shape. Indeed, the topside break in the 30-minute relative strength index dampens the likelihood of seeing a short-term correction in the index, and the bullish sentiment underlining the reserve currency may gather pace as it continues to benefit from safe-haven flows. However, we may see the greenback consolidate over the coming days as market participants look forward to the U.S. Non-Farm Payrolls report due out on Friday, and the report may ultimately trigger a short-term correction in the greenback should it foster speculation for additional monetary support.
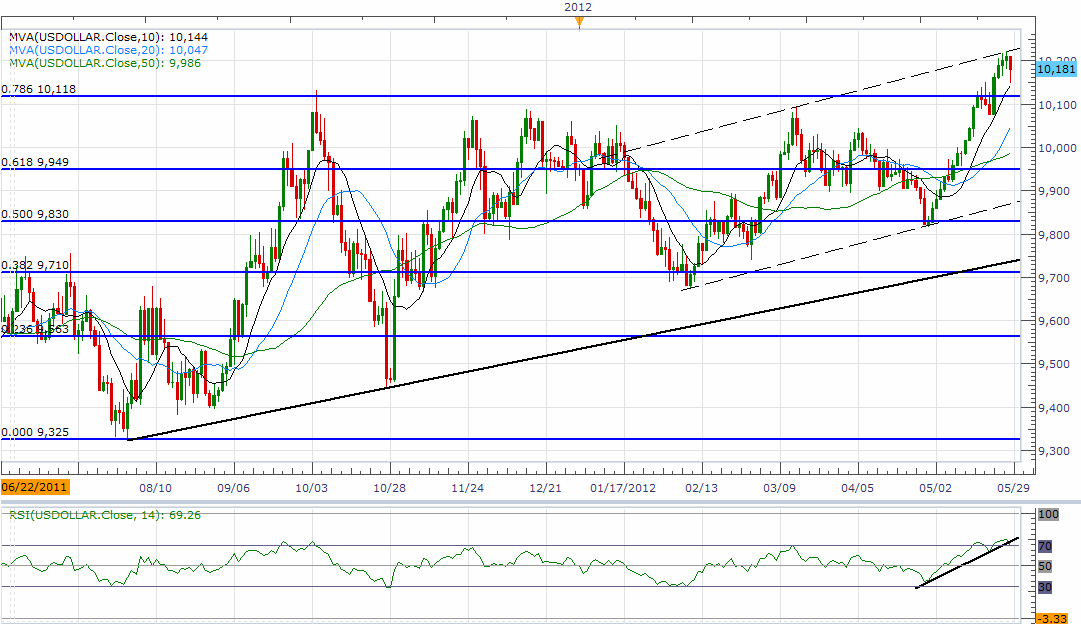
USD_Eyes_Fresh_Highs_Ahead_Of_Correction_JPY_Preserves_Bullish_Trend_body_ScreenShot052.png, USD Eyes Fresh Highs Ahead Of Correction, JPY Preserves Bullish TrendAs the USDOLLAR comes off of the upper bounds of the ascending range, the daily chart continues to foreshadow a short-term correction, and we will keep a close eye on the relative strength index as it fails to maintain the upward trend from the beginning of the month. As the oscillator comes back from overbought territory, a move below 70 could pave the way a larger move to the downside, but we will look for a higher low in the index as it maintains the upward trending channel from earlier this year. In turn, we may see the dollar revert back to the 61.8 percent Fibonacci retracement around 9,949, but it’s imperative that the greenback holds above the 9,900 figure to maintain a bullish outlook for the USD. In turn, we will be looking to buy dips as we head into June, and the upward trend in the reserve currency may continue to gather pace in the second-half of the year as the Federal Reserve moves away from its easing cycle.
USD_Eyes_Fresh_Highs_Ahead_Of_Correction_JPY_Preserves_Bullish_Trend_body_ScreenShot053.png, USD Eyes Fresh Highs Ahead Of Correction, JPY Preserves Bullish Trend The greenback weakened across the board on Monday, led by a 0.85 percent advance in the Australian dollar, while the Japanese Yen climbed 0.29 as the Bank of Japan talked down speculation for additional asset purchases. Indeed, the policy meeting minutes reiterated that the BoJ is not monetize government debt as market participants look for more easing, and it seems as though the central bank will carry its current policy into the second-half of the year even as Governor Masaaki Shirakawa pledges to pursue ‘powerful’ monetary easing. As the USDJPY threatens the downward trend carried over from March, we are looking for a close above the 20-Day SMA (79.75) to see a meaningful rebound in the exchange rate, and we will be closely watching the 79.00 figure as it appears to be holding up as support.

> The objectives United States senior fresh as Forex high volatility dollar

The US Dollar (ticker: USDOLLAR) continues to hit multi-year highs against the Euro and other counterparts. Risk of reversal is high as sentiment is extreme, but we encourage the purchase of the US Dollar, dips and EURUSD sales rallies.
Conditions of currency pair DailyFX person and bias of business strategy
forex_trading_forecast_market_conditions_body_Picture_1.png, US Dollar Targets Fresh Highs as Forex Volatility Elevated
The Dollar American signals (ticker: USDOLLAR) rally defied to the expectations in the speed and magnitude, and a strong jump in the expectations of the volatility of the market forex options suggests she could continue.
Our trade of "Breakout Opportunities" (Breakout2) based on the volatility of the system signals is that our strategy favoured in this market moves. Indeed, such a system still is when our reading "Volatility Percentile" struck above 75%. It is based on a canal évasion forex trading system, which, according to our automated commercial research means to do well in active markets. Similarly, our research shows that trading systems low volatility range do poorly in such market conditions, and as caution is recommended.
High volatility promotes same specific to other currencies that we usually associate strong currency moves with the fear of the investor. Specifically, we are promoting the purchase of the US Dollar and Japanese Yen against the Australian High performance Dollar and Dollar New Zealand sanctuary.
Recent data CFTC commitment of traders show as large speculators recently struck their more net-long of US Dollars against the Euro (short EURUSD) in history. Very biased sense prevents expressed blows could be brutal and caution is recommended. Yet, we believe that the broader trend is clear, and the US Dollar remains ready to challenge the maximum charge.
Market conditions:
Expectations of the volatility of the market Forex options continue near their highest levels of the year, and these calls supported for currency workshops give us firm belief in our calls for banging. In this environment avoid us the trading range (attempt of choice above or below) and trade with the broader market trends.

forex_trading_forecast_market_conditions_body_Picture_2.png, US Dollar Targets Fresh Highs as Forex Volatility Elevated-Written by David Rodriguez, strategist of DailyFX.com Quantitative
To contact David, e-mail drodriguez@dailyfx.com
To be added to the list of electronic distribution of David for this and other reports, e-mail line of the "Distribution list" topic to drodriguez@dailyfx.com
Definitions
Percentile volatility: the more higher, more you can see the price movements. This number tells us where implied aware of levels of volatility standing in what concerns the past 90 days of trading. We have found that the implied volatilities tend to remain very high or very low for long periods of time. As such, it is useful to know where the current implied volatility level lies in its range in the medium term.
Trend-, this indicator measures the intensity trend in telling us where the price stands on its 90 - day trading range. A very low number tells us that the price is currently at or near monthly minimum, while a larger number, we said that we are near the top. A value at or near 50%, said us that we are in the monthly range of the currency pair.
High range – 90 days of high fence.
Low range - low closing of 90 days.
Last - the current market price.
Bias - the criteria above, we believe the most likely cost-effective strategy for any given currency pair. A currency pair very volatile (Percentile of high volatility) suggests that we must use strategies of evasion. More moderate volatility levels and high values of trend to more attractive momentum trades, while the lowest indicator figures flight Percentile and tendency to make Trading Range the more attractive strategy.
HYPOTHETICAL RESULTS HAVE MANY INHERENT LIMITATIONS, SOME ARE DESCRIBED BELOW. NO REPRESENTATION IS MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFITS OR LOSSES SIMILAR TO THOSE SHOWN. IN FACT, IS OFTEN THE DIFFERENCES BETWEEN HYPOTHETICAL PERFORMANCE RESULTS AND THE RESULTS OBTAINED LATER BY ANY PARTICULAR COMMERCIAL PROGRAM.
ONE OF THE LIMITATIONS OF HYPOTHETICAL RESULTS IS THAT THEY ARE GENERALLY PREPARED WITH THE RECOIL. IN ADDITION, HYPOTHETICAL EXCHANGE DOES NOT INVOLVE FINANCIAL RISK, AND NO HYPOTHETICAL TRADING RECORD CAN COMPLETELY EXPLAIN THE IMPACT OF FINANCIAL RISK IN ACTUAL TRADING. FOR EXAMPLE, THE ABILITY TO WITHSTAND LOSSES OR TO ADHERE TO A PARTICULAR DESPITE LOSS OF BUSINESS TRADING PROGRAM IS POINTS OF MATERIAL THAT MAY ALSO AFFECT THE COMMERCIAL REAL RESULTS. THERE ARE NUMEROUS OTHER FACTORS RELATED TO THE MARKETS IN GENERAL OR TO THE IMPLEMENTATION.
ANY SPECIFIC TRADING PROGRAM WHICH CANNOT BE FULLY RECORDED IN THE PREPARATION OF HYPOTHETICAL RESULTS AND WHICH MAY IMPAIR AN EXCHANGE REAL-TIME RESULTS. All opinions, news, research, analyses, prices or other information contained on this Web site are provided in the General market commentary and is not investment advice. The FXCM group accepts no liability for any loss or damage, including without limitation, any loss of profit, which may arise directly or use where dependency contained within the trading signals, or any graphical analysis accompanying indirectly.

Thursday, May 24, 2012

€ Euro Sets Fresh 2-Year Lows as Manufacturing and Service Outputs Shrink

24 May 2012 08:40 GMT THE TAKEAWAY: EC PMI Manufacturing down to 45.0, PMI Services down to 46.5 -> German business confidence slows on worries over Greece -> Euro sets new 2-year lows
It’s more bearish news for the Eurozone as production and manufacturing sectors both dropped in May more than expected. The purchasing managers index for manufacturing was down to 45.0 from 45.9 in April, instead of an expected rise in manufacturing. The composite index for services was down to 46.5 from 46.9 the previous month, instead of the expected 46.7, according to Markit Economics. Any level underneath 50 indicates a contraction.
Europe’s biggest economy and main backer of austerity contributed to the manufacturing drop. Germany’s index for manufacturing came in at 45.0 for May, way below the expected 47.0. However, Germany’s services output improved as the PMI came in at 52.2, above the expected 52.0 for March. Earlier today, France’s services and manufacturing were both reported to be contracting faster than expected.
The drop in output could support those who want to scale back austerity measures in Europe and instead stimulate growth to battle the severe debt levels.
The debt crisis seems to be worrying German businesses. German IFO current assessment came in lower than expected at 113.3 for May. IFO expectations was also at a lower than expected 100.9. The negative German manufacturing and business confidence follows an earlier confirmation of the country’s economic expansion in Q1 of this year.

euro_pmi_body_eurusd.png, Euro Sets Fresh 2-Year Lows as Manufacturing and Service Outputs ShrinkEURUSD set new 2-year lows at 1.2515 following the weak PMI’s before snapping back up above the previous support level at 1.2544.
DailyFX provides forex news and technical analysis on the trends that influence the global currency markets.
Learn forex trading with a free practice account and trading charts from FXCM.
24 May 2012 08:40 GMT

Wednesday, May 23, 2012

€ Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate Trade

Fear and uncertainty take hold of markets Price action reminiscent of Bear and Lehman Investors continue to price in probability for Greek exit Euro breaks to fresh 2012 lows; no signs of bounce Bank of Japan leaves policy on hold as widely expected BOE Minutes reveal 8-1 vote to keep rates steady; retail sales very weak Fear and uncertainty are the ultimate market poison, and of course, the ongoing European turmoil has fueled both. Market participants don’t seem to be thinking clearly, in a way reminiscent of the US environment in the early crisis days when Bear Stearns and Lehman collapsed.
We don’t blame them. European leaders are dragging their feet on Greece, and the longer markets wait for a solution, the more investors will price-in a Greek default and Euro exit. The next step is only logical - instead of speculating if Greece will egress, market players are now wondering how messy the fallout will be.
And naturally, currencies have been feeling the brunt of all this. Price action has seen resurgence in broad based buying of the US Dollar and Yen on a flight to safety, while risk correlated assets have been aggressively sold. Any rebound in the early week following some already aggressive risk selling in recent sessions has already been well offered, and the risks from here continue to be tilted to the downside. In fact, it is actually rather surprising that the Euro has only just now broken down through the yearly lows from January at 1.2625. The EU Summit today could inspire some fresh volatility, and we will be watching closely for any positive developments. Still, we recommend that market participants take to the sidelines and patiently wait for the panic and fear to subside.
Relative performance versus the USD Wednesday (as of 10:50GMT)
JPY +0.72%
GBP -0.22%
CAD -0.23%
CHF -0.26%
EUR -0.27%
AUD -0.62%
NZD -0.63%
Elsewhere, the Bank of Japan has come out and left policy on hold as was widely expected. While the central bank did cite ongoing risks to the global economy, perhaps some upbeat comments towards the local economy were poorly mistimed given the escalation in global fear over the past 24 hours and recent Fitch downgrade of Japan. Unfortunately for the administration, this will only add to additional upside pressure on the Yen, which still trades rather close to its record highs against many currencies. Meanwhile, comments from the former Greek PM that both a Greek exit or austerity would both be quite painful, have not helped matters, while an abysmal UK retail sales print was also digested in the European session.
Technically, risk correlated assets are already well oversold on the daily charts, and it will be interesting to see just how stretched these markets can get before any sign of rebound. Aussie and Kiwi have both dropped to fresh multi-day lows against the buck, and yet both of these currencies are already well oversold on the short-term charts. The Euro is also oversold and yet, given the fundamental outlook above, things could still get much uglier. Normally, we might recommend looking to fade the risk off trade, but given just how scary markets are right now, the best place is probably on the sidelines. It is true that there is no money to be made on the sidelines, but sometimes, the best trade is no trade at all.
ECONOMIC CALENDAR

Euro_Drops_to_Fresh_2012_Lows_Fear_and_Panic_Dominate_Trade_body_Picture_5.png, Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate TradeTECHNICAL OUTLOOK

Euro_Drops_to_Fresh_2012_Lows_Fear_and_Panic_Dominate_Trade_body_eur.png, Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate TradeEUR/USD:The market remains under intense pressure with the market finally taking out the 2012 lows from January at 1.2625. While we would not rule out a possibility of a sustained break below this level over the coming sessions, short-term technical studies are correcting from oversold and are showing a need for some form of a bounce from where a fresh lower top is sought out. Ultimately however, any rallies should now be very well capped by previous support turned resistance at 1.3000 in favor of additional weakness over the medium-term that projects deeper setbacks into the lower 1.2000's.

Euro_Drops_to_Fresh_2012_Lows_Fear_and_Panic_Dominate_Trade_body_usd.png, Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate TradeUSD/JPY:The market continues to consolidate around 80.00 and is in the process of looking for a medium-term higher low ahead of the next major upside extension back above the yearly highs at 84.20 and towards 90.00 further up. However, for the time being it remains in question whether the market will still head lower towards the 200-Day SMA by 78.50 before ultimately reversing higher. The key level to watch above comes in by 80.60, and a break and close above this level will officially alleviate downside pressures and suggest that a higher low has now been carved in the 79.00's.

Euro_Drops_to_Fresh_2012_Lows_Fear_and_Panic_Dominate_Trade_body_gbp.png, Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate TradeGBP/USD:The market remains under intense pressure since breaking back below 1.6000 and setbacks could now extend towards next key support in he 1.5600 area over the coming sessions. Still, daily studies are now stretched and we would prefer looking to sell into rallies towards 1.6000 where a fresh lower top is sought out.

Euro_Drops_to_Fresh_2012_Lows_Fear_and_Panic_Dominate_Trade_body_usd_1.png, Euro Drops to Fresh 2012 Lows; Fear and Panic Dominate TradeUSD/CHF:Overall the structure remains highly constructive and we continue to project additional upside over the coming months back above parity. For now, the latest break and close above 0.9335 is expected to accelerate gains for a retest of the yearly highs by 0.9600, while any intraday pullbacks should be very well supported ahead of 0.9200. Ultimately, only back under 0.9000 would negate outlook and give reason for pause.

Wednesday, May 9, 2012

:Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead

08 May 2012 10: 55 GMT Risk rallies viewed as technical corrections; look to sell Euro consolidating above 1.3000 ahead of next drop Investors digesting implications of latest French and Greek elections Spain back in focus as the country attempts to rescue local bank German industrial production comes in well above consensus Australian government announces return to budget surplus Although we have seen a bit of a bounce in risk correlated assets, we contend that the rally is nothing more than some minor consolidation ahead of the next wave of risk liquidation. The Euro managed to close back above 1.3000 on Monday, but from here, we expect any additional rallies to be very well capped ahead of 1.3200 in favor of an eventual retest of the 2012 lows from January at 1.2620. Market participants are still digesting the weekend election results out of France and Greece, and there is a good deal of concern as to whether the newly elected governments will acceded to the austerity measures imposed to ease the debt crisis. In Greece, the situation is highly uncertain, with the lack of a clear majority potentially creating a situation where austerity measures might be significantly reduced in order to appease the opposition. Elsewhere, Spain is back in the headlines, as the country attempts to rescue its third largest bank.
Relative performance versus the USD Tuesday (as of 10: 45GMT)
JPY - 0.21 %
CHF + 0.17 %
EUR + 0.21 %
GBP + 0.30 %
CAD + 0.43 %
NZD - 0.54 %
AUD - 0.59 %
Moving on, economic data continues to show signs of weakness, and the softer results once again highlight the fragile state of affairs in which the global economy lies. Nevertheless, the Euro did manage to hold above 1.3000 in European trade, aided by some solid auction results and a very impressive German industrial production print. Meanwhile, our Euro / Sterling long position (long @ 0.8050) found some bids on softer overnight RICS house price data, while in Australia, the government announced the country would return to a budget surplus of $A1.5B in 2012/2013. Still, overall, we expect risk correlated currencies and global equities to be very well offered on any rallies in favor of more bearish price action.
ECONOMIC CALENDAR
Currency_Rallies_Viewed_As_Corrective_Fresh_US_Dollar_Upside_Ahead_body_Picture_5.png, Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead
TECHNICAL OUTLOOK
Currency_Rallies_Viewed_As_Corrective_Fresh_US_Dollar_Upside_Ahead_body_eur.png, Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead
EUR/USD: The market has finally cleared some key support by 1.3000 and the break opens the door for deeper setbacks over the coming days towards the 2012 lows from January at 1.2620. However, short-term technical studies will need to unwind from oversold readings before we are to see any extended declines below 1.3000, and we recommend looking to sell into rallies into the 1 3150 - 1 3200 where a fresh lower top is now sought. Ultimately, only back above 1.3300 would delay.
Currency_Rallies_Viewed_As_Corrective_Fresh_US_Dollar_Upside_Ahead_body_usd.png, Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead
USD/JPY: The latest pullback from the 2012, UST highs is viewed as corrective and it looks as though the market could still see a bit more weakness before considering the possibility for the formation of a medium-term higher low. Overall, this is a market that has undergone a major structural shift in recent months and we now see the pair in the early stages of a longer-term up-trend. Ultimately, only a weekly close back under 78.00 would negate.

Currency_Rallies_Viewed_As_Corrective_Fresh_US_Dollar_Upside_Ahead_body_gbp.png, Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead
GBP/USD: Finally starting to see signs of a medium-term top and potential 2012 high after the market has stalled and retreated from the area 1.6300. Key support now comes in by 1.6075 and a break and closed below this level will confirm bearish bias and accelerate declines towards 1.5800 further down. Ultimately, only a break back above 1.6300 would negate and give reason for reconsideration.
Currency_Rallies_Viewed_As_Corrective_Fresh_US_Dollar_Upside_Ahead_body_usd_1.png, Currency Rallies Viewed As Corrective; Fresh US Dollar Upside Ahead
USD/CHF: Our core constructive outlook remains well intact with the latest setbacks very well supported by psychological barriers at 0.9000. It now looks as though the market could be looking to carve a fresh higher low, and we will be looking for additional upside back towards the recent range highs at 0.9335 over the coming sessions. Above 0.9335 should then accelerate gains towards the 2012 highs by 0.9600 further up. Ultimately, only back under 0.9000 delays and gives reason for pause.

Friday, April 27, 2012

:: Spanish Downgrade and the Bank of the Japan Action inspire fresh volatility

27 April 2012 06: 20 GMT S & P downgrades Spain two notches to BBB PM Rajoy comments contribute to risk off price action Yen sees whipsaw price action post new BOJ measures SNB back in focus. keeping an eye on EUR/CHF Risk correlated assets have come under pressure into Friday trade following the news of the latest S & P downgrade of Spain's credit rating by two notches to BBB. Comments from Spanish PM Rajoy that the country's ability to fund itself isat risk and that budget cuts are necessary due to an unmanageable deficit, also have not helped matters. As a result, the Euro has come under some added pressure, with the single currency trading back below 1.3200.
Elsewhere, the Yen was subjected to some highly choppy whipsaw trade after the Bank of Japan announced additional monetary easing measures. Although the BOJ left rates on hold as expected, the Yen was sold off after the asset purchase fund was raised by Y10 trillion (net Y5 trillion as Y5 trillion fixed rate operation was reduced), and the maturity of the purchasing JGBs was extended to 3 years.
However, any initial Yen weakness on the announcement was easily absorbed, with USD/JPY more than giving back its post event risk rally. The broader macro theme of risk off trade proved to be the more influential market mover and perhaps sent a message that government action can not have any lasting influence on currency management.
This offers a good segue into the subject of Swiss intervention, and we would remind investors to not forget about the EUR/CHF cross rate, which has been unable to establish any upside momentum beyond 1.2000, despite firm warnings from the SNB that the 1.2000 floor will be aggressively defended. The recent Yen rally post BOJ moves can not be comforting to the SNB, and just might provide enough ammunition for Swiss long to ramp up their efforts. While we are not necessarily calling a EUR/CHF 1.2000 break today, we also will be keeping a close eye.
Overall, we would still recommend trading with extreme caution in these very tight directionless markets. Despite the pullback, the market still seems to be very well supported Euro on dips, and we would still not rule out the possibility for a reversal back above 1.3200 and towards 1.3300. We are very bearish once 1.3300 is tested, but at current levels, we remain supervised. Ultimately, it will be attitude towards risk that overlooked market direction. Any pick up in risk appetite will be Euro and positive currency (USD and potentially negative Yen), while added fear and uncertainty will likely weigh on the FX markets and benefit the US Dollar.

>> Weakness of fresh Scandi begins to materialize as expected

EUR/Sek Setbacks have once again been very well supported ahead of the 8.75 level and the market looks to once again be attempting to carve a bottom in favor of renewed strength back towards the 8.90 area over the coming sessions. Ultimately, only back below 8.75 negates and gives reason for concern.
USD/Sek Remains very well supported on any form of a dip, and risks from here are for continued strength back towards the recent multi-day range highs by 6.88. A break above will accelerate further, while only back below 6.57 delays.
USD/Nok Although the market has been confined to a multi-day consolidation, dips have been very well supported and we continue to see evidence of an eventual break of this range to the upside. Look for a push back above 5.28 to confirm bias and accelerate gains. Only back under 5.65 would delay and give reason for concern.
EUR/NokLooks to be finally attempting to establish some form of a base after being very well offered over the past several weeks. The latest break back above 7.49 triggered a double bottom which has already reached its 7.60 objective area. From here, look for additional gains towards 7.75 over the coming weeks. Ultimately, only back under 7.45 delays.d charts from FXCM.

Monday, April 23, 2012

€€€ Euro highlights Extension open to fresh near weekly increase

23 April 2012 05: 56 GMT  Euro in puts positive weekly close; fresh upside ahead Yen finds renewed bids; purpose should be once again well offered China HSBC PMIs improve; help to supportive risk off dips Sarkozy takes hit in weekend election. renforce it Euro Aussie producer prices much softer; increases chances for rate cut We have seen a fairly quiet start to the week, with most currencies consolidating recent gains against the buck. However, Friday's bullish close in the Euro above 1.3215 does now open the door for fresh upside over the coming sessions back above 1.3300. Meanwhile, the Yen has been the one standout in Monday trade, with this currency reversing course and finding renewed bids. USD/JPY has broken back below Friday's low to end a sequence of consecutive daily higher lows. Nevertheless, any setbacks in this major could be limited, and the improved overnight China HSBC Flash PMIs have helped to support pullbacks.
Moving on, the fallout from the French election could factor in Monday trade, with incumbent Sarkozy putting to a poor showing over the weekend. Elsewhere, Australian PPI data came in much softer than expected earlier today, and the commodity currency has been a relative underperformer on the back of this news. The development increased the likelihood of a rate cut at the upcoming meeting. The producer price results now set the stage for the more important ICC release due tomorrow.
ECONOMIC CALENDAR
Euro_Puts_in_Bullish_Weekly_Close_to_Open_Fresh_Upside_Extension_body_Picture_5.png, Euro Puts in Bullish Weekly Close to Open Fresh Upside Extension
TECHNICAL OUTLOOK
Euro_Puts_in_Bullish_Weekly_Close_to_Open_Fresh_Upside_Extension_body_eur.png, Euro Puts in Bullish Weekly Close to Open Fresh Upside Extension
EUR/USD: The latest round of setbacks have stalled ahead of some key multi-week support by 1.3000 and from here we still can not rule out risks for additional consolidation above 1.3000, before considering bearish resumption. Friday's close above 1.3215 opens the door for additional earnings over the coming sessions but ultimately, any rallies towards 1.3400 should be well capped. A break and closed daily back under 1.3000 is now required to put pressure back on downside and accelerate declines to the early 2012 lows at 1.2660.
Euro_Puts_in_Bullish_Weekly_Close_to_Open_Fresh_Upside_Extension_body_usd.png, Euro Puts in Bullish Weekly Close to Open Fresh Upside Extension
USD/JPY: The latest pullback from the 2012, UST highs was viewed as corrective and it looks as though the market has finally found some solid support ahead of 80.00. The setbacks have stalled by the top of the daily and weekly Ichimoku clouds and we look for the formation of a fresh medium-term higher low somewhere around 80.00 ahead of the next major upside extension back towards and eventually through UST. Overall, this is a market that has undergone a major structural shift in recent months and we now see the pair in the early stages of a longer-term up-trend. Ultimately, only a weekly close back under 78.00 would negate. Any dips towards 80.00 should therefore be used as formidable buy opportunities.
Euro_Puts_in_Bullish_Weekly_Close_to_Open_Fresh_Upside_Extension_body_gbp.png, Euro Puts in Bullish Weekly Close to Open Fresh Upside Extension
GBP/USD: The recent break back above 1.6000 now opens the door for fresh upside towards the October 2011 peak at 1.6165. However, any additional gains beyond 1.6165 should prove hard to come by, and we once again see risks for a bearish reversal in favor of renewed weakness back down towards key support by 1.5800. A break and closed below 1.5800 will then accelerate declines. Ultimately, only a weekly close above 1.6165 would negate underlying bearish bias.
Euro_Puts_in_Bullish_Weekly_Close_to_Open_Fresh_Upside_Extension_body_usd_1.png, Euro Puts in Bullish Weekly Close to Open Fresh Upside Extension
USD/CHF: Our core constructive outlook remains well intact, with the latest setbacks very well supported by psychological barriers at 0.9000. It now seems as though the market could be looking to carve a fresh higher low, and we will be watching for additional upside back towards the recent range highs at 0.9335 over the coming sessions. Above 0.9335 should accelerate gains towards the 2012 highs by 0.9600 further up. Ultimately, only back under 0.9000 delays and gives reason for pause.

Friday, April 13, 2012

Euro Relief Rally To Set Lower Top, Sterling Eyes Fresh Highs

12 April 2012 13:35 GMT  Talking Points
Euro: ECB Softens Dovish Tone, Italy Bond Auction Disappoints British Pound: Poised For Fresh Yearly High As Upward Trend Gathers Pace U.S. Dollar: Index Eyes 9,900 For Support, Fed Officials In Focus Euro:ECB Softens Dovish Tone, Italy Bond Auction Disappoints
The Euro climbed to a fresh weekly high of 1.3175 as the European Central Bank pledged to ‘address upside risks to medium-term price stability in a firm and timely manner,’ but we are likely to see the Governing Council take additional steps to shore up the ailing economy as the sovereign debt crisis continues to heighten the risk for a prolonged recession. Indeed, Italy sold EUR 2.88B in 3-year bonds versus the EUR 3.00B target, while the government offered 3.89% on its debt, which compares to the 2.76% yield seen in March.
Meanwhile, ECB board member Joerg Asmussen argued that commercial banks in Ireland need to ‘substantial’ reduce their reliance on central bank funding, and it seems as though the Governing Council is looking to preserve a wait-and-see approach throughout the remainder of the year as it maintains its one and only mandate to ensure price stability. However, the ECB may have little choice but to expand policy further as the debt crisis continues to drag on investor confidence, and the threat for contagion may bring about another wave of non-standard measures as the governments operating under the single currency become increasingly reliant on monetary support. As there appears to be a descending triangle in the EURUSD, we will maintain our bearish outlook for the pair, and we may see the pair carve out another lower top ahead of May as the relative strength index maintains the downward trend from earlier this year. In turn, the short-term rebound in the exchange rate may provide a selling opportunity for FX traders, and we should see 1.3000 ultimately give way as the debt crisis continues to dampen the fundamental outlook for the region.
British Pound: Poised For Fresh Yearly High As Upward Trend Gathers Pace
The British Pound extended the advance from earlier this week amid the rise in risk-taking behavior, and we expect to see fresh yearly highs in the GBPUSD as the upward trending channel continues to take shape. However, as the economic docket is expected to show easing price pressures in the U.K., we may see the GBPUSD consolidate going into the end of the week, and we will look to buy the pair on a pullback as it carves out a higher low in April. As the Bank of England is scheduled to release its policy meeting minutes next week, the fresh batch of central bank rhetoric could set the stage for another move to the upside, and we may see the sterling outperform against its major counterparts should the Monetary Policy Committee continue to soften its dovish tone for monetary policy.
U.S. Dollar: Index Eyes 9,900 For Support, Fed Officials In Focus
The greenback tumbled lower on Thursday, with the Dow Jones-FXCM U.S. Dollar Index (Ticker: USDOLLAR)slipping to a fresh weekly low of 9,913, and the reserve currency may track lower throughout the North American trade as the U.S. equity market continues to pare the decline from earlier this week. As the rise in risk-taking behavior gathers pace, we may see the dollar index fall back towards 9,900 to test for interim support, and the slew of central bank rhetoric on tap for later today may help to prop up the greenback should Fed officials talk down speculation for additional monetary support. Indeed, we will be closely watching the remarks from FOMC voting members William Dudley and Sarah Bloom Raskin as central bank officials take note of the more robust recovery, and we may see the committee continue to soften its dovish tone for monetary policy as the fundamental outlook for the world’s largest economy improves.
Friday, March 2, 2012

TradeTheNews.com European Market Update: ECB deposits hit fresh record levels following 3-year LTRO operation

 Friday, March 02, 2012 5:49:18 AM TradeTheNews.com European Market Update: ECB deposits hit fresh record levels following 3-year LTRO operation***Economic Data***
- (RU) Russia Narrow Money Supply w/e Feb 27th (RUB): 6.85T v 6.84T prior
- (EU) ECB: €572M borrowed in overnight loan facility v €3.0B prior; €776.9B parked in deposit facility (fresh record high) vs. €475.2B prior - (DE) Germany Jan Retail Sales M/M: -1.6% v +0.5%e; Y/Y: 1.6% v 0.2%e
- (FI) Finland Q4 GDP Q/Q: 0.1%e v 0.9% prior; Y/Y: 1.3%e v 2.7% prior
- (HU) Hungary Dec Final Trade Balance: €325.0M v €352.1M prelim
- (ES) Spain Feb Net Unemployment M/M: +112.3K v +80.0Ke
- (ZA) South Africa Feb Naamsa Vehicle Sales Y/Y: 6.4% v 6.5%e
- (NO) Norway Jan Retail Sales Volume Y/Y: 6.7% v 2.6%e
- (UK) Feb PMI Construction: 54.3 v 51.3e
- (EU) Euro Zone Jan PPI M/M: 0.7% v 0.5%e; Y/Y: 3.7% v 3.5%e
- (IT) Italy 2011 Annual GDP: 0.4% v 0.3%e; Deficit to GDP:% v 4.0%e
*** SPEAKERS/FIXED INCOME/FX/COMMODITIES/ERRATUM ***
***Notes/Observations***
- EU's Juncker: There is a plan B if the Greece debt swap fails
- Fed's Williams: More stimulus needed if recovery falters
- Euro Zone Leaders pave way for EU decision on Greek bailout agreement
- China diversifies away from USD
- Germany MoM Retail Sales disappoints
- Spanish Feb Net Unemployment climbs more than expected
Equities: FTSE 100 -0.10% at 5925, DAX flat at 6942, CAC-40 +0.20% at 3508, IBEX-35 +0.50% at 8592, FTSE MIB +0.60% at 16,926, SMI +0.10% at 6135
- European shares rallied lifted by a stronger banking sector which is up following ECB's LTRO allotment this week and press reports that EU leaders may agree to provide capital faster to the €500B permanent bailout fund. EU leaders may pay the first two installment this year and complete the capitalization in 2015, which is one year ahead of the schedule. Goldman Sachs also boosted the financial sector by upgrading European banks to Overweight
- Areva [CEI.FR] , as expected from yesterday's EU session, reported a €2.0B net loss due to provisions, the first loss in its history. However the company reiterated its outlook and noted that it aimed to raise at least €1.2B from asset sales in 2012-13 period. Meanwhile, the company agreed to sell both its stake in Eramet and in Canadian Millenium. Rentokil [RTO.UK] traded down after reporting its earnings and noted that its H1 performance in one of its units would continue to be disappointing.
Speakers: - The European fiscal compact was signed by 25 EU leaders. EU's President Van Rompuy stated that the measure would restore trust among EU states
- Germany Econ Min: Roesler commented in the German press that the supported the idea of placing a European Commissioner in charge of economic development in Greece but could not understand Greek objections to the proposal. He observed that the Greek people were aware of the needed sacrifices, but the Greek elite did not want to give up their privileges.
- BOJ Yamaguchi commented that the central bank might need new tools for its 1% CPI target and was flexible and ready to move if necessary. He noted the BOJ was not thinking about unwinding measures nor saw the need at this time to extend JGB period under program
- Japan Public Pension Fund (GPIF) (world's largest) reported its Oct-Dec qtr returns which rose by 0.58% compared to a prior loss of-3.32% q/q. It noted that it's posted a profit of ¥618.7B due to returns on foreign stocks. Assets at Jan end to head down to ¥108.1T.
- S&P EMEA managing director Fernandez de Heredia commented that Italy could return to an 'A' rating if country moved in the right direction regarding its debt, its growth and reforms. The first step by the rating agency would entail a change of Italy's outlook from negative to stable which depended on the debt, growth and the economic impact of the reforms of PM Monti's government. If Italy goes in the right direction, S&P wouldl take this first step. The recent decrease seen in govt' yields were not enough for the outlook to change, only sustainable impact of the reforms on growth can change the outlook
- Japanese purchasers seek force majeure clause in the event it was unable to pay Iran, or lift Iranian crude for lack of ship insurance coverage
Currencies:
- Concerns that the EU Leaders were waiting for the final outcome of the Greek PSI swap on March 9th and weaker German retail sales data pressured the EUR/USD from the getgo of the session. The record amount of deposits in the ECB's facility seemed to mirror the net new borrowing from the recent 3-year lending LTRO and prompted concerns whether bank would actually lend to assist the real economy.
- The EUR/USD tested 1.3240 before stabilizing in the session but was off some 505 pips from its Asian opening levels.
- The JPY weakness stalled during the mid-morning after testing 81.71. The higher oil prices said to be another factor weighing against the JPY currency sentiment as Japanese demand for oil surged after last year nuclear disaster.
Political/ In the Papers:
- The FT commented on concerns in Germany about the growth of the Bundesbank's balance sheet. The state bank's Target2 balance is about €500B, which reflects the amount that the German central bank has lent to the ECB. According to Commerzbank, Target2 claims are the largest part of the Bundesbank's balance sheet. As a reminder, Target2 is the joint gross clearing system of the ESCB that unifies the technical infrastructure of the 26 central (note-issuing) banks of the EU.
- Prosecutors in Germany raided various properties across Europe as part of an insider trading probe related to allegations that certain investors tried to inflate prices for penny stocks. German officials raided 53 properties in Germany and inquired about 29 other sites outside of Germany.
- The Telegraph's Ambrose Evans-Pritchard suggested that the recent European unemployment data shows a widening prosperity gap between the Northern and Southern EU economies. SocGen analyst Klaus Baader believed the EU's austerity measures are having a more negative than expected impact on the EU's labor markets, particularly in the peripheral countries.
- In an IMF report to the G20 ministers last weekend in Mexico, it was recommended that the ECB lower the target rate to less than 1% in addition to emergency loans to commercial lenders. Monetary policy needed to be kept highly accommodative, which the IMF said could be done by lowering the target policy rate (where there is still room), and by more unconventional measures if necessary.
- In its Credit Review Office (CRO) quarterly report on SMEs, the Ireland Finance Ministry targeted new lending requirements for both Allied Irish and Bank of Ireland. The new plan will require each bank to lend €3.5B in 2012, followed by an additional €4B each in 2013. Lending can take the form of new loans or restructuring old debt.
***Looking Ahead*** - (EU) EU Leaders Summit in Brussels
- (ES) Spain to present new budget targets
- 8:30 (CA) Canada Dec Gross Domestic Product M/M: +0.3%e v -0.1% prior; Y/Y: 1.9%e v 2.0% prior; Quarterly GDP Annualized GDP Y/Y: 1.8%e v 3.5% prior
- 9:45 (US) Feb ISM New York: No est v prior
- 10:00 (DK) Denmark Feb Foreign Currency Reserves (DKK): No est v 492.6B prior
- 16:00 (CO) Colombia Feb Producer Price Index M/M: No est v -0.5% prior; Y/Y: No est v 3.7% prior
- 20:00 (CN) China Feb Non-Manufacturing PMI: No est v 52.9 prior
- 20:00 (US) Fed's Bullard speaks on U.S. Economy in Vancouver
Weekend
Sat: (US) Republican Washington Caucus
Sun 18:00 (EU) Bank of International Settlements (BIS) holds Global Central Bank Meeting
Sun (RU) Russia Presidential Election Legal disclaimer and risk disclosure All information provided by Trade The News (a product of Trade The News, Inc. "referred to as TTN hereafter") is for informational purposes only. Information provided is not meant as investment advice nor is it a recommendation to Buy or Sell securities. Although information is taken from sources deemed reliable, no guarantees or assurances can be made to the accuracy of any information provided. 1. Information can be inaccurate and/or incomplete 2. Information can be mistakenly re-released or be delayed, 3. Information may be incorrect, misread, misinterpreted or misunderstood 4. Human error is a business risk you are willing to assume 5. Technology can crash or be interrupted without notice 6. Trading decisions are the responsibility of traders, not those providing additional information. Trade The News is not liable (financial and/or non-financial) for any losses that may arise from any information provided by TTN. Trading securities involves a high degree of risk, and financial losses can and do occur on a regular basis and are part of the risk of trading and investing.